


Table of Contents
Getting a tax bill you can’t comfortably pay is an uncomfortable situation. When the balance reaches $10,000 or more, it can be tempting to put the problem aside and hope you can deal with it later.
That usually isn’t a good long-term plan.
If you owe the IRS money and cannot pay the entire balance, there are several ways you may be able to address the debt. The right option depends on your income, expenses, assets, filing history, and other details of your situation.
The IRS itself provides several programs for taxpayers who cannot immediately pay their full balance.
Start by Finding Out Exactly What You Owe
Before looking for a solution, make sure you understand the balance.
Tax debt can involve more than the original tax amount. Interest and penalties may also be included, and the total can change over time.
If you received an IRS notice, read it carefully and check which tax year or years are involved. You can also use your IRS Online Account to review information about your federal tax account.
This step may seem basic, but knowing exactly what you owe makes it much easier to evaluate your options.
You May Not Have to Pay Everything at Once
If you have $10,000 or more in tax debt, that does not automatically mean you need to produce the entire amount immediately.
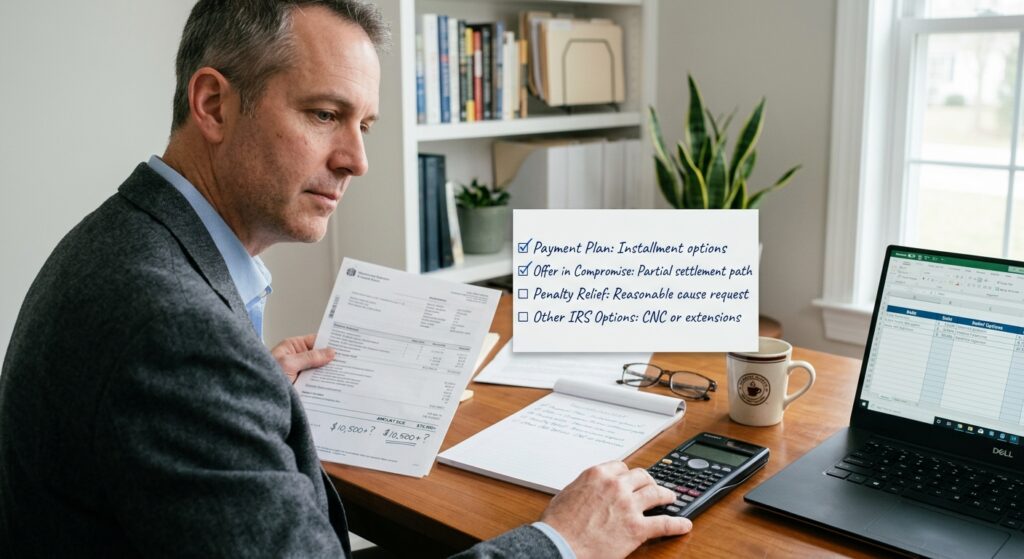
The IRS offers payment plans that allow eligible taxpayers to pay their balance over time. Depending on the circumstances, taxpayers may qualify for short-term or long-term arrangements.
For someone with regular income but not enough savings to cover a large tax bill, spreading payments over time may be worth investigating.
There are costs and requirements associated with some payment arrangements, so it’s important to look at the actual terms rather than assuming a payment plan will work the same way for everyone.
What If You Can’t Afford the Full Balance?
This is where things become more individual.
The IRS has an option called an Offer in Compromise (OIC). In qualifying cases, an OIC can allow a taxpayer to settle a tax debt for less than the full amount owed.
However, having a large tax balance by itself does not mean someone qualifies.
The IRS considers factors including a taxpayer’s ability to pay, income, expenses, and available asset equity. It also has eligibility requirements, including requirements related to filing tax returns and certain payments.
So if you see an advertisement suggesting that anyone with $10,000 in tax debt can simply have their bill reduced, be careful. The amount you owe is only one part of the eligibility picture.
Penalties Are Another Part of the Problem
When dealing with tax debt, it is useful to distinguish between the underlying tax and penalties.
The IRS provides penalty-relief programs for taxpayers who meet certain requirements. Depending on the circumstances, reasonable cause and other criteria may be relevant.
Penalty relief does not necessarily eliminate the underlying tax balance. It is therefore worth understanding exactly what type of relief you are seeking before making a decision.
What If You Can’t Pay Right Now?
Some taxpayers are in a situation where even a payment plan isn’t realistically affordable.
The IRS says that taxpayers who cannot currently pay may, in some circumstances, qualify for a temporary delay in collection. This does not erase the tax debt, and interest and penalties can continue to apply.
Financial hardship can be complicated to document, so this is an area where understanding your individual circumstances matters.
Don’t Ignore IRS Notices
One of the easiest mistakes to make is simply avoiding the problem.
If you receive an IRS notice, don’t assume that not responding will make the debt disappear. The IRS notes that interest can continue to accrue and additional penalties may apply in certain circumstances.
Depending on the circumstances, other collection actions may also become relevant.
If you cannot pay the amount requested, that is different from having no options. It is generally better to find out what options are available than to ignore the correspondence.
When Does Professional Help Make Sense?
You don’t necessarily need to hire someone just because you owe the IRS money. The IRS provides information and tools directly to taxpayers, including resources for payment plans and Offers in Compromise.
Professional assistance may nevertheless be something to consider if your situation is difficult to understand or involves several tax years, collection notices, complicated finances, or questions about which option fits your circumstances.
If you decide to speak with a tax-debt company, take some time to understand what services it actually provides and what fees may apply. Ask questions before agreeing to anything.
One Option You Can Investigate
If you’re looking for professional assistance, CuraDebt is one company that connects consumers with tax-relief providers in its network. CuraDebt’s affiliate information says its tax referrals are matched with independent tax-relief firms whose professionals may include Enrolled Agents, CPAs, or tax attorneys.
Affiliate disclosure: This article contains affiliate links. If you use an affiliate link and subsequently become a customer, we may receive compensation at no additional cost to you.

A Simple Way to Think About Your Situation
If you owe $10,000 or more, start with a few basic questions:
Can I pay the balance in full without creating another financial problem?
If yes, paying the balance may be the simplest approach.
Could I reasonably make monthly payments?
If so, an IRS payment plan may be worth investigating.
Is paying the full balance unrealistic because of my financial circumstances?
If so, research whether an Offer in Compromise or another collection option could apply.
Are penalties contributing significantly to what I owe?
Look into whether you may qualify for penalty relief.
Am I dealing with a situation I don’t understand?
Consider getting professional advice and compare the information you receive with the official IRS guidance.
The Bottom Line
A $10,000 IRS balance is significant, but the number alone doesn’t tell you which solution is appropriate.
Some taxpayers can resolve their debt through a payment plan. Others may qualify for different forms of relief. An Offer in Compromise can reduce the amount paid in qualifying cases, but it is not automatic and the IRS evaluates each situation individually.
The most useful first step is to understand your actual balance and look at the options available to you.
If you’re considering professional assistance, compare your choices carefully, read the terms, and make sure you understand what you’re being offered before moving forward.